
Wealth planning
Connect family priorities, ownership, liquidity and succession in a plan that can be understood, implemented and revisited.
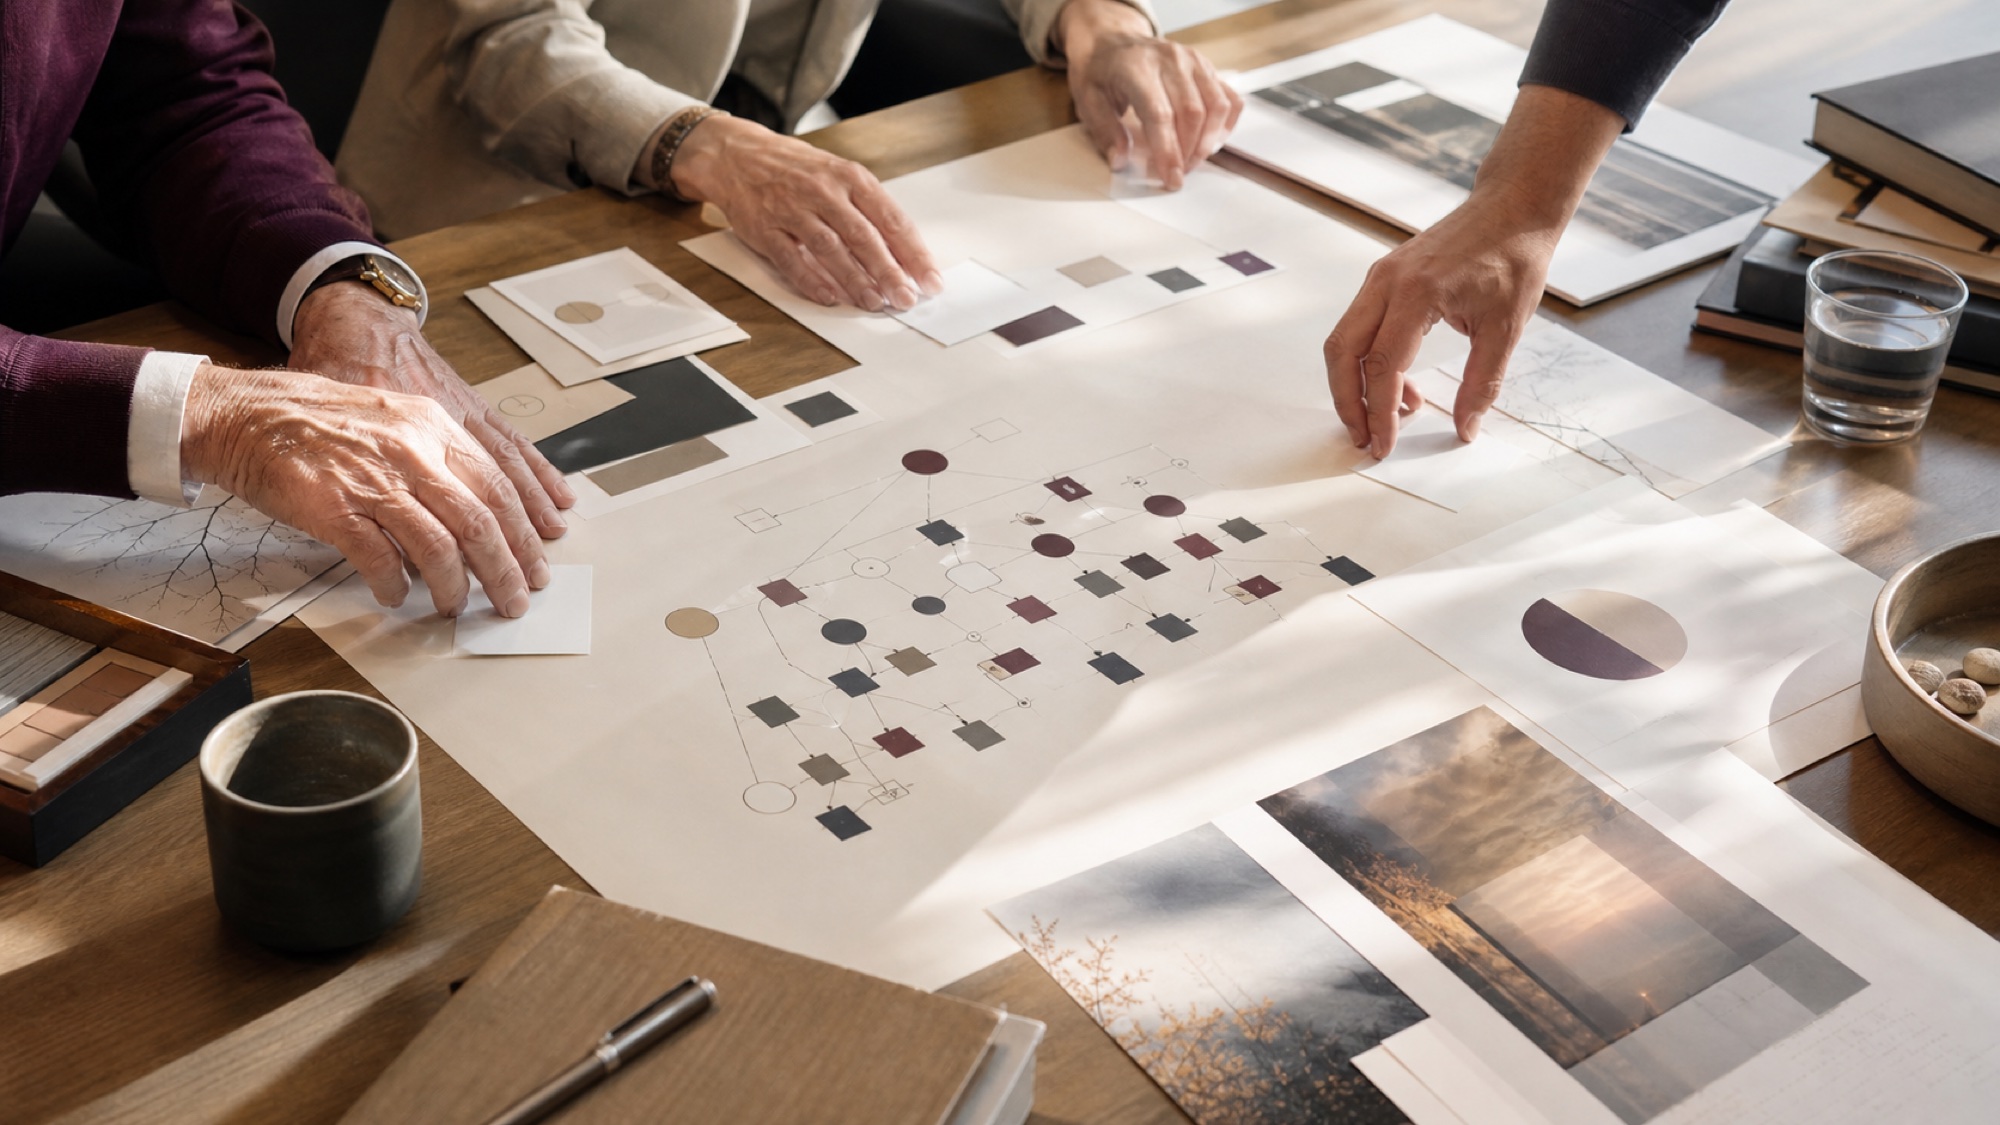
A clear view.
A considered plan.
Wealth planning brings the whole balance sheet into the conversation: investments, an operating business, property, borrowing, future commitments and the people who depend on them. The starting point is a clear understanding of what the family wants its capital to accomplish, including where priorities differ between generations.
A planning mandate should set out the work to be undertaken, the decisions reserved to the client and the role of external advisers. Availability depends on the relationship, jurisdiction and agreed scope. Legal drafting and tax conclusions belong with appropriately qualified advisers; coordination does not replace their advice.
01When a planning review is useful
A business sale, inheritance, change in residence or new family responsibility can make an existing arrangement less suitable. A review can also help when assets have accumulated across institutions and ownership vehicles without a shared picture of obligations. The trigger need not be a transaction: uncertainty about who can make a decision is itself worth addressing.
Bring the questions that are difficult to resolve in isolation. How much capital can remain invested? What happens if a principal becomes unavailable? How should an operating business and personal portfolio be considered together? Which commitments belong to which entity? The work begins by identifying these questions, rather than selecting products.
02The planning process
Discovery establishes ownership, objectives, cash-flow needs, jurisdictions and existing advisers. The next stage identifies dependencies: a proposed ownership change may require legal work, while an investment decision may depend on a tax estimate or transaction receipt. Priorities and responsibilities should be agreed before implementation begins.
A working plan then records the options considered, decisions made and actions still open. Implementation proceeds through the people and institutions with the necessary authority. The final review checks that documents, account authorities and practical arrangements reflect the intended outcome. A signed document alone does not demonstrate that an arrangement can operate.
03Family governance and succession
Governance clarifies participation, information and authority. A family charter, meeting process or decision map can help, but the level of formality should reflect the family's needs. Separate family membership, ownership rights and management roles, particularly where a business remains central to the balance sheet.
Succession planning should address both an orderly transition and an unexpected absence. It can include an adviser contact map, continuity instructions, a review of access rights and a schedule for future decisions. The relevant legal instruments and any changes to ownership require specialist advice and valid approvals.
04Liquidity and commitments
Map expected spending, liabilities, private-investment commitments and contingent receipts by owner, date and currency. Identify assets that are restricted or cannot readily be sold. This makes it possible to discuss long-term investment without overlooking the resources needed for near-term obligations.
Borrowing may be considered where appropriate to an agreed relationship, but it introduces interest costs, conditions and repayment risk. Portfolio-backed borrowing can lead to additional collateral requirements or asset sales following a decline in collateral value. It should be evaluated alongside alternatives, not treated as a substitute for liquidity planning.
05Philanthropy and purpose
Giving decisions benefit from a separate statement of objectives, a budget and a review process. Consider the work required to administer a structure, the needs of recipients and the roles family members want to take. A foundation or other vehicle is a means of organising purpose, not an objective in itself.
Cross-border arrangements can affect eligibility, reporting and tax treatment. Discuss them before making commitments. Keep charitable resources and obligations visible in the wider plan without assuming they can be used interchangeably with personal assets.
06What a useful planning record contains
- A map of ownership, assets, liabilities and material commitments.
- Objectives, constraints and questions requiring specialist advice.
- A decision register with owners, dependencies and target dates.
- A liquidity calendar and continuity contact list.
- Review triggers for changes in family, residence or business circumstances.
The format and deliverables are agreed for each mandate. A focused review may need a concise decision paper; a complex transition may require several linked workstreams. The value lies in making responsibilities clear and decisions implementable.
07Preparing for an introduction
Start with your country of residence, the broad ownership structure and the decision you need to make. Do not send identity documents, account statements or detailed financial records through an unverified channel. A referrer should arrange an introduction through an established contact before confidential material is exchanged.
Content reviewed 14 September 2026
Every relationship
begins with a conversation.
New relationships begin through established referrals. Share the question you are considering; the appropriate scope and jurisdiction come next.
Arrange an introductionHelp for existing clients